Flood Zones in SLO County: Where They Are and What They Cost
Updated: 2 days ago
The Central Coast has a reputation for drought, so the phrase "flood zone" surprises people. Then a wet winter arrives, creeks that were dry in September fill the culverts, and everyone remembers that this county is a series of watersheds running from the hills to the sea. If you are buying here, a flood designation is one of the first things we look up on any property, and this post explains why and what to do with the answer.
THE BASICS
What a flood zone actually is
Flood zones are mapped by FEMA on Flood Insurance Rate Maps. The designations that matter most to a homebuyer:
Special Flood Hazard Areas, usually labeled with an A or V, represent land with a meaningful annual chance of flooding. If a lender is involved, flood insurance is mandatory in these zones.
Moderate and minimal risk zones, typically labeled X, are outside the high-hazard area. Insurance is optional but available, and in shaded X zones the risk is real enough that many owners carry it.
Two things to keep in mind. First, maps get updated, and a property can move in or out of a zone when they do. Second, a map is a model.
Homes outside a mapped zone have flooded during Central Coast storms, and homes inside one have stayed dry for decades. The designation drives the paperwork; local knowledge drives the judgment.
ACROSS SAN LUIS OBISPO COUNTY
Where flood zones show up in San Luis Obispo County
We are not going to pretend to list every parcel, but there are places where flood questions come up in nearly every transaction.
Oceano and the Arroyo Grande Creek corridor
Oceano is the county's best-known flood-conscious community. The town sits low, near the lagoon and the mouth of Arroyo Grande Creek, behind a levee system, and it has experienced significant flooding in big storm years. Buyers in Oceano should expect a flood designation on many streets, factor insurance into the budget, and read the disclosure package carefully. Our post on living in Oceano is honest about this trade-off alongside the town's real value.

Downtown San Luis Obispo and the creek neighborhoods
San Luis Obispo Creek runs right through downtown, and the city has a long flood history along it and along its tributaries. Blocks near the creek in the Mid-Higuera area, parts of the Railroad District, and low-lying streets near Laguna Lake and Prefumo Creek carry designations. Many of these are wonderful, walkable neighborhoods, and the flood question is a budgeting item rather than a deal-breaker.
The Salinas River corridor
From Santa Margarita through Atascadero, Templeton, Paso Robles, and San Miguel, the Salinas River and its tributaries define a floodplain. Properties near the river, and along creeks like Atascadero Creek and Paso Robles Creek, may fall inside a mapped zone even when the river looks like a dry sandy wash most of the year. In wet winters it is not.
Coastal creek mouths
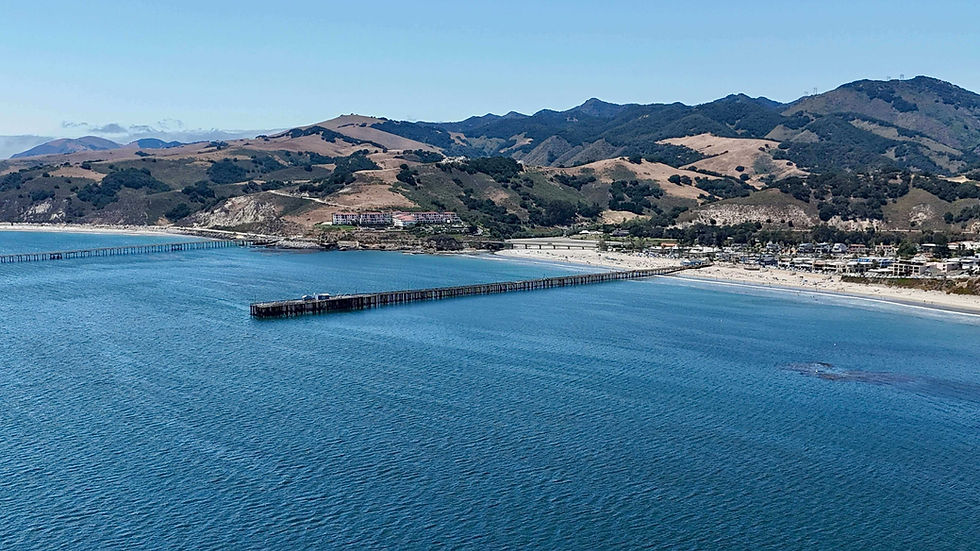
Morro Bay near Morro Creek and Chorro Creek, Cayucos along Cayucos Creek, Cambria along Santa Rosa Creek, and Avila Beach where San Luis Obispo Creek meets the ocean all have low areas with designations. Los Osos has zones along Los Osos Creek and near the bay's edge.
The Nipomo and Santa Maria River lowlands
South of the Mesa, the flat land toward the Santa Maria River carries flood mapping, mostly agricultural but with some residential parcels.
INSURANCE · LENDING · RESALE
What a designation costs you
The costs fall into a few buckets, and none of them are the same for every home.
Flood insurance. Written through the National Flood Insurance Program or private carriers. Premiums depend on the zone, the home's elevation relative to the base flood elevation, the foundation type, and the coverage amount.
A home with a documented elevation certificate showing it sits above the base flood level can cost far less to insure than one without. We ask sellers for any existing certificate, and we budget for one if it does not exist.
Lender requirements. If the home is in a Special Flood Hazard Area and you are financing, the lender will require a policy in place at closing and will escrow for it. Plan for this early, because it affects your monthly payment.
Construction and remodel rules. Cities and the county regulate building in floodplains. Substantial improvements to a home in a mapped zone can trigger requirements to elevate or floodproof. Buyers planning a major remodel or an ADU should understand this before they buy, and our post on remodeling in SLO County discusses the permit process.
Resale. A designation follows the property, and the next buyer will do the same math you did. It does not make a home unsellable, but it narrows the pool a little and it needs to be priced honestly.
HOW WE LOOK AT IT
How we evaluate a property in a flood zone
Pull the current FEMA map and the exact zone for the parcel, not just the neighborhood.
Ask the seller for an elevation certificate, past flood insurance declarations, and any history of water in the house or on the lot.
Read the natural hazard disclosure report, which will state the flood designation and other mapped hazards.
Walk the property after a rain if we can, and look at grading, drainage, sump pumps, and where the neighbors' water goes.
Get flood insurance quotes during the contingency period, alongside fire and homeowners quotes. Our post on homeowners insurance beyond fire explains how they fit together.
Check whether recent or planned levee, creek, or drainage projects affect the risk or the mapping.

WHEN IT’S WORTH IT
When a flood zone is worth it
Some of the best-located homes in San Luis Obispo County sit near water, because that is where towns were built. A creekside lot downtown, a home a block from the bay in Los Osos, or an Oceano house with the dunes at the end of the street can be exactly the right purchase with the risk priced in and the insurance handled. The wrong purchase is the one where the buyer learns about the designation from the lender in week three of escrow.
Water finds the low ground every winter. We want to know where that is before you own it.
Next step
If a home you are watching sits near a creek, a river, a lagoon, or the bay, send us the address and we will pull its flood mapping and hazard disclosure before you spend a weekend on it. Then you can decide with the real cost in front of you. Our home inspection post covers the drainage findings that usually go with it, and our contact page is where to send the address.

Talk With Kim & Kristen
We are Kim San Jule and Kristen Gentry, Broker Associates with Real Broker, serving San Luis Obispo County and the Central Coast. Whether you are buying, selling, or simply thinking ahead, we are glad to be a resource.
Kim San Jule · Broker Associate, DRE 01948144 · 805-345-8303 · kimsanjule@gmail.com
Kristen Gentry · Broker Associate, DRE 01968754 · 805-441-4618 · kristengentryslo@gmail.com
Real Broker · Search Central Coast homes for sale